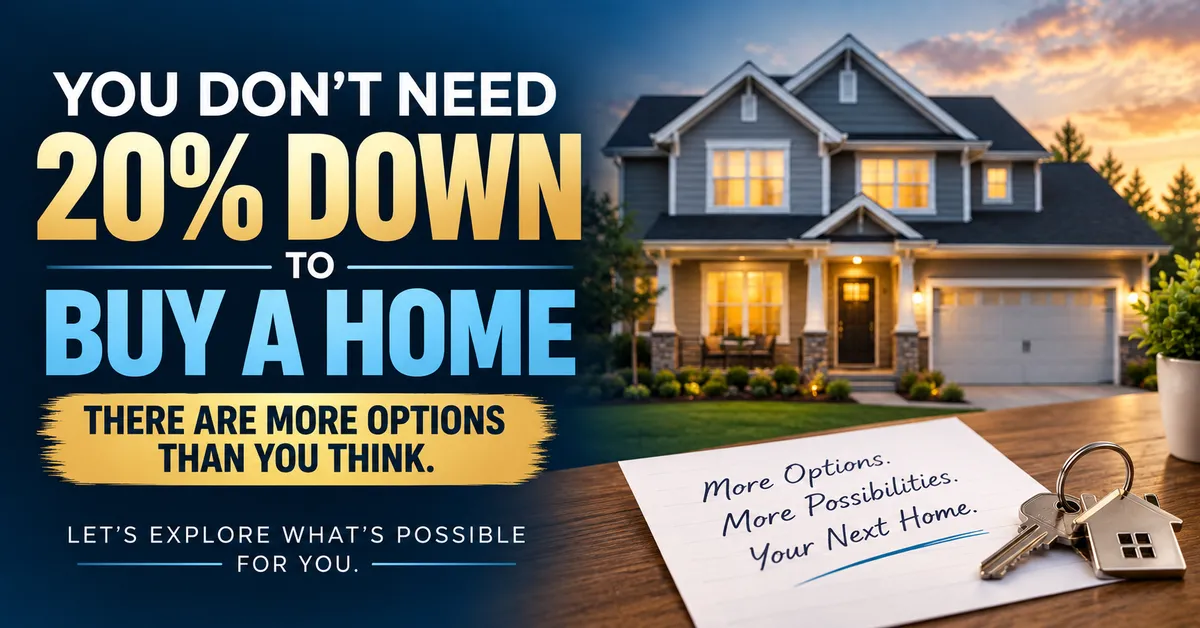
You Do Not Need 20 Percent Down to Buy a Home and This Belief Is Holding Too Many Buyers Back
The Assumption That Is Delaying Homeownership for More Buyers Than Any Other
Josiah Burdge hears it consistently. Buyers who are ready in almost every way but believe they cannot start the process until they have saved twenty percent of a purchase price that keeps moving higher. That belief is the single biggest thing holding many qualified buyers back from homeownership and it is not accurate.
What the Twenty Percent Myth Actually Costs
When a buyer sets a twenty percent down payment as the entry requirement they are setting a savings target that can represent years of additional renting. On a four hundred thousand dollar home twenty percent is eighty thousand dollars. On a five hundred thousand dollar home it is one hundred thousand. Those are not numbers most buyers accumulate quickly and while they save the home prices they are targeting often continue to appreciate.
The delay has a real financial cost that most buyers never calculate because they are focused on the target rather than the alternatives.
What the Actual Options Look Like
The mortgage market offers multiple paths to homeownership that do not require twenty percent down. VA loans for eligible veterans and service members require zero down payment in most cases and carry no private mortgage insurance requirement. USDA rural development loans offer zero down options for qualifying buyers in eligible geographic areas. FHA loans allow qualified buyers to purchase with as little as three and a half percent down. Conventional loan programs start as low as three percent down for qualifying first-time buyers depending on the specific program and the borrower profile.
Down payment assistance programs add another layer of flexibility. State, county, and municipal programs exist across the country specifically to help buyers who meet income and purchase price requirements cover part or all of the required down payment. A significant number of buyers who would qualify for these programs have never checked because they assumed the twenty percent standard was the only path available.
Seller concessions in the current market add further opportunity. Sellers who are motivated to close are contributing toward closing costs more frequently than they were during the peak of the seller's market. Those contributions reduce the cash a buyer needs to bring to closing and can make the total upfront requirement dramatically more manageable than the twenty percent figure implies.
Why the Conversation Has to Come Before the Assumption
Every buyer's situation is different. The right combination of loan program, down payment assistance, and negotiating strategy looks different for each person and the only way to know what is actually available is to have the conversation rather than making assumptions based on a number that does not reflect the current landscape of programs.
The first step is not saving forever toward a target that may be far larger than necessary. It is understanding what options are actually available for your specific situation right now.
Reach out to Josiah Burdge to find out what the real path to homeownership looks like for you. You may be much closer than you think.
Sources
ConsumerFinancialProtectionBureau.gov
HUD.gov
FannieMae.com
MortgageNewsDaily.com
Investopedia.com