Stop Assuming a Price Reduction Is the Best Thing a Seller Can Give You and Here Is Why
The Negotiating Question Most Buyers Are Getting Wrong
When buyers find a home they like and want to negotiate the first question is almost always the same. How much can we get them down on price? It feels like the right question. It is actually the incomplete question and Josiah Burdge wants to show you why asking it alone could be costing you real money every month.
What a Ten Thousand Dollar Price Reduction Actually Produces
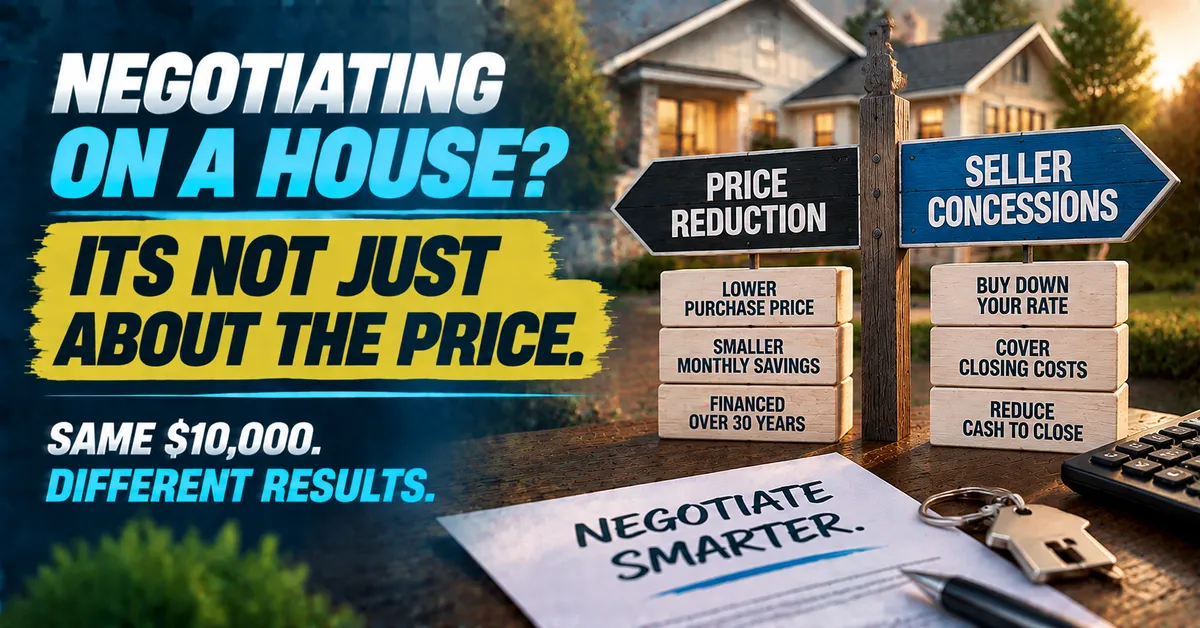
Take a five hundred thousand dollar home. You negotiate ten thousand dollars off the price. That sounds like a meaningful win. But when you finance that ten thousand dollar reduction over thirty years the monthly savings is approximately fifty to sixty dollars. Real money over the life of the loan but not the significant monthly impact most buyers picture when they imagine negotiating ten thousand dollars off a purchase price.
The seller contributed ten thousand dollars worth of value to make the deal work. The buyer received fifty to sixty dollars per month in benefit. That is one way to use the seller's money. It is not always the best way.
What the Same Ten Thousand Dollars Can Do as a Seller Concession
Take that same ten thousand dollars and negotiate it as a seller concession rather than a price reduction. Depending on the loan program being used those funds can be applied in ways that produce a dramatically different result for the buyer.
Applied toward permanently buying down the interest rate the monthly payment benefit can reach one hundred to one hundred and fifty dollars or more. The rate reduction applies for the life of the loan and the monthly savings compounds in a way that a price reduction of the same dollar amount simply cannot match.
Applied toward closing costs the ten thousand dollars reduces the cash the buyer needs to bring to the table at closing. For a buyer who is qualified on income but running tight on liquid funds that is not a fifty dollar per month benefit. It is the difference between the purchase being possible right now versus having to wait.
Applied toward a temporary rate buydown the concession creates a reduced payment in the early years of the loan when the budget adjustment to homeownership is often the most challenging.
Same ten thousand dollars. Completely different result depending on how it is structured.
The Better Question to Ask Before Negotiating
Do not just ask how much can we get them down on price. Ask your lender and your agent what the most valuable way to use the seller's money actually is for your specific situation.
The answer depends on your loan program, your down payment, the contribution limits that apply, and what your biggest financial pressure point is. Whether that is the monthly payment, the cash required at closing, or the purchase price itself determines which structure produces the best outcome for you.
That is the question Josiah Burdge is here to help you answer before the offer is written rather than after it is already submitted. Give him a shout with any questions about your specific scenario.
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
Investopedia.com
BankRate.com