Buying Your Next Home Before You Sell Your Current One Might Be the Right Move Right Now
The Strategy That Sounds Backwards Until You Run the Numbers
If you own a home and want to move the conventional wisdom says sell first then buy. Wait until you know exactly what you have before you commit to the next thing. Josiah Burdge wants you to hear a different way of thinking about this because in the current market the conventional approach may actually be leaving money on the table.
Why the Current Market Changes the Equation
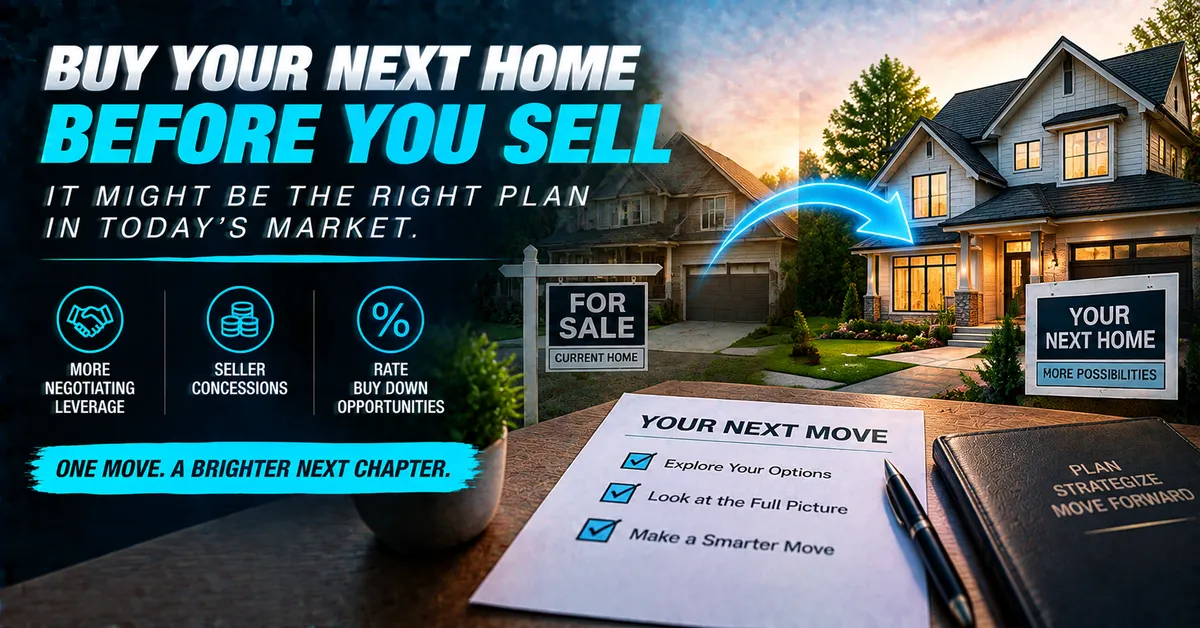
Buyers have more negotiating leverage right now than they have had in years. Homes are sitting longer. Sellers are adjusting prices. Concessions toward closing costs and rate buydowns are being negotiated in transactions that would not have offered any flexibility two or three years ago.
That leverage is available to you as a buyer on your next home right now. The question is whether you are positioned to use it.
The Math That Might Surprise You
Here is the framework worth thinking through. Suppose you are planning to sell your current home for six hundred thousand dollars before buying your next one. Now suppose that instead of treating those as two separate transactions you look at the entire move as one.
What if you negotiate your next home twenty thousand dollars below what you expected to pay. What if you also negotiate ten thousand dollars in seller concessions on top of that. You have just created thirty thousand dollars in value on the purchase side of the equation before the sale side even closes.
That thirty thousand dollars in purchase-side savings changes what you need from the sale of your current home to end up in the same financial position you originally planned. You may be able to sell your current home for less than you originally targeted and still arrive at closing on the new home in essentially the same place you wanted to be. The two sides of the transaction work together rather than being evaluated independently.
The Financing Strategies That Make This Realistic
Buying before you sell is not just a conceptual framework. There are specific financing strategies that make it a practical possibility for homeowners in the right situation. Bridge financing, leveraging existing equity, and structuring contingencies appropriately are all tools that can make the timeline work without requiring the sale to close before the purchase begins.
The details depend on the specific equity position, the price points involved, and the gap between the current home value and the next purchase. That is the conversation worth having before assuming the conventional sell-first sequence is the only option.
The Mistake Worth Avoiding
Treating the sale and the purchase as two completely separate transactions is the most common mistake Josiah sees homeowners make in this situation. They are really one move. Evaluating them together rather than independently reveals opportunities that the sequential approach hides entirely.
If you are in this situation or if you have a client who is reach out to Josiah Burdge for a quick conversation about whether the numbers can be customized to get them into the home they actually want to be in.
Sources
NAR.realtor
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
FannieMae.com
Investopedia.com